
Rolled-up holiday pay means holiday pay is added on top of normal wages instead of being paid when leave is taken. Since 2024, it's lawful in the UK only for irregular-hours workers and part-year workers, using 12.07% of pay in each pay period.
You may have seen the issue appear suddenly in your payroll routine. A seasonal worker's payslip includes a separate holiday pay line, while a regular employee's does not. Someone asks why their pay is different when they take annual leave, and you need to know whether the arrangement is lawful, correctly calculated and clearly explained.
The answer depends on more than the label in your payroll software. You need to identify the worker's actual pattern, check the start of the relevant leave year, apply the correct calculation and show the payment transparently. The 2024 reforms made rolled-up holiday pay available in limited circumstances, but they didn't turn it into a universal shortcut.
Table of Contents
- Why Rolled Up Holiday Pay Confuses So Many Employers
- How Rolled Up Holiday Pay Works in Practice
- The Legal Journey From Banned to Conditionally Allowed
- The Real Advantages and Drawbacks to Weigh Up
- Choosing Between Rolled Up Pay and Traditional Accrual
- Compliance Practices Every Small Business Should Follow
- Making Holiday Pay Simple and Compliant
Why Rolled Up Holiday Pay Confuses So Many Employers
An HR administrator at a growing business might reasonably hesitate after spotting “holiday pay” on a casual worker's payslip. The business employs seasonal staff, zero-hours workers and people who only work during part of the year. The payroll provider has added an extra payment to some payslips, but nobody is entirely sure whether that's permitted or whether every employee should receive the same treatment.
Rolled-up holiday pay is a method of paying holiday pay alongside ordinary wages. Instead of paying the worker for annual leave when they take time away from work, the employer adds the holiday pay to the worker's pay for work completed during the pay period.
That timing creates the first major point of confusion. A worker receiving rolled-up holiday pay might get more in a week when they work, but they shouldn't expect a separate holiday payment when they later take leave. The money has already been paid through earlier payslips, although the worker's entitlement to take leave still needs to be managed.
The classification question comes first
Since the 2024 reforms, the method is restricted to irregular-hours workers and part-year workers. A regular-hours employee can't have holiday pay folded into their hourly rate under this arrangement. The difference between a qualifying worker and a non-qualifying worker therefore matters before anyone presses “run payroll”.
A worker's contract and working pattern need careful review. “Part-time” doesn't automatically mean “part-year”, and a worker who sometimes works extra shifts isn't automatically an irregular-hours worker. Treating every variable employee as eligible can expose the business to underpayment disputes and corrective payroll work.
What this guide helps you decide
You'll find the mechanical calculation, a worked payslip example, the legal change that took effect in 2024, and a practical comparison with traditional holiday pay. The focus is the decision employers face: who qualifies, how the payment should appear, and whether rolled-up pay is suitable for the workforce you manage.
How Rolled Up Holiday Pay Works in Practice
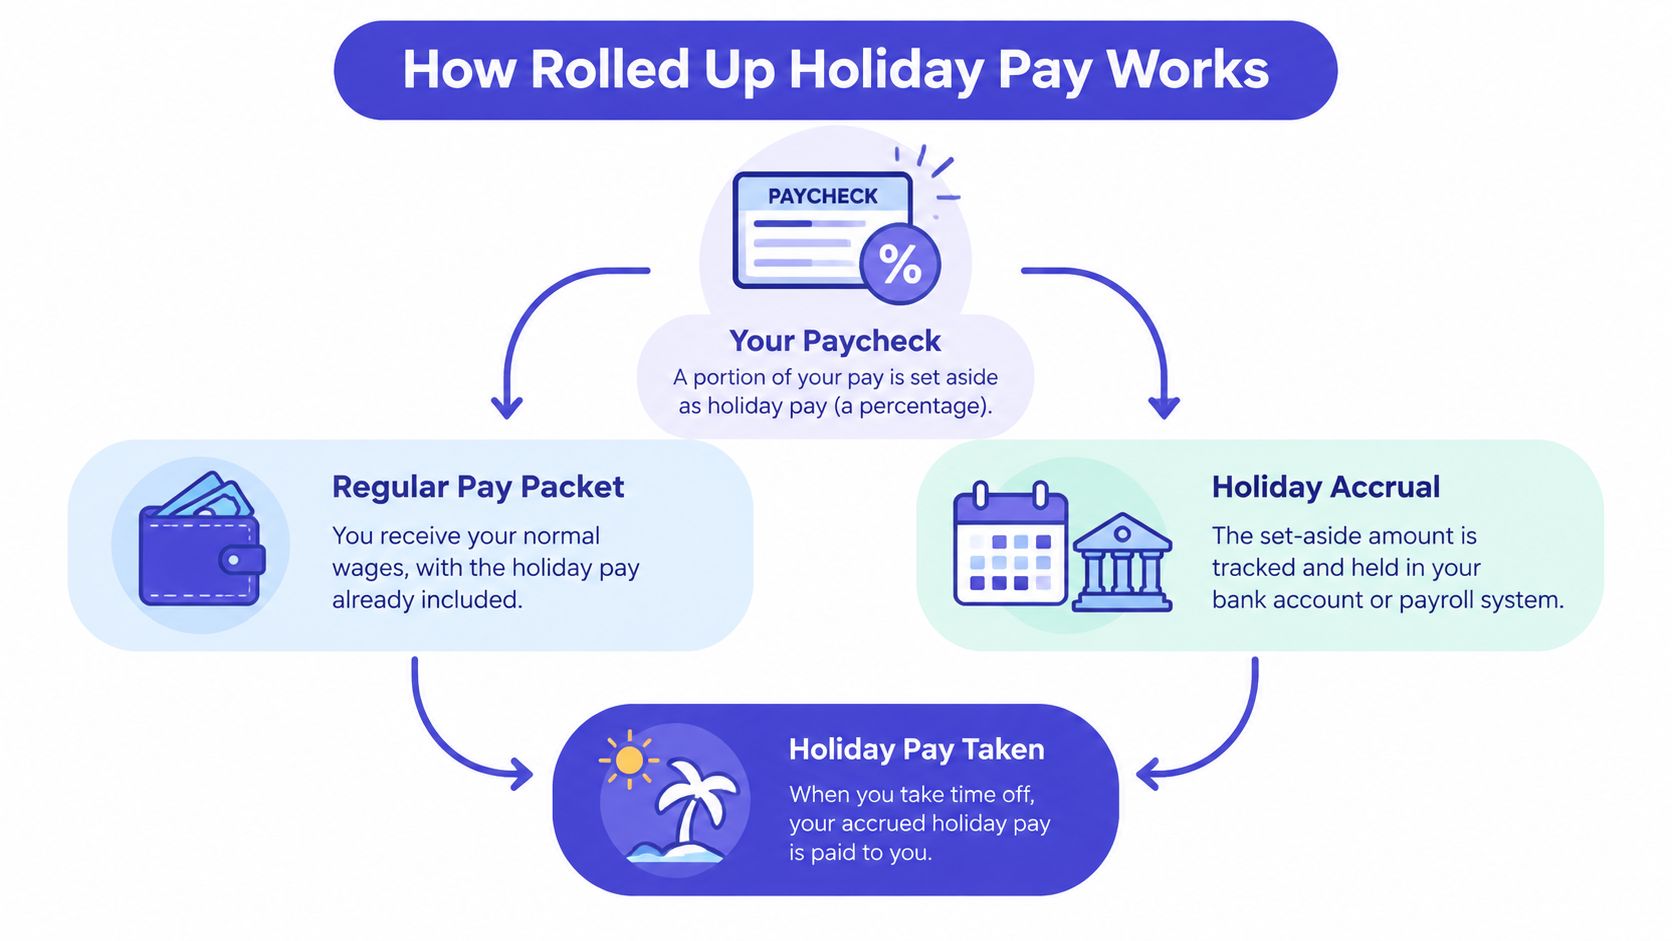
Think of rolled-up holiday pay as putting the holiday payment into each relevant pay packet rather than waiting until the worker takes leave. The worker still takes annual leave, but the money associated with that leave arrives progressively while they work.
For the statutory minimum entitlement, the calculation uses 12.07% of the worker's total pay in each pay period. The ACAS guidance on rolled-up holiday pay explains that the figure reflects 5.6 weeks of statutory holiday divided by 46.4 working weeks.
Core definition: Rolled-up holiday pay is holiday pay added to wages for work done, paid at the same time as those wages, rather than paid when annual leave is taken.
The process is straightforward once eligibility has been established.
- Identify the worker's relevant pay for the period. Use the total pay on which the holiday calculation is based.
- Apply 12.07%. Multiply the relevant pay by 0.1207.
- Pay it with the wages. The holiday element belongs in the same pay period as the work-related payment.
- Show it separately. The payslip must identify holiday pay as its own line, rather than hiding it inside a higher hourly rate.
A worked payslip example
Suppose an eligible irregular-hours worker receives £1,000 in relevant pay during a pay period. The holiday pay calculation is:
£1,000 × 12.07% = £120.70
The payslip could therefore show:
| Payslip line | Amount |
|---|---|
| Pay for work completed | £1,000.00 |
| Rolled-up holiday pay | £120.70 |
| Total gross pay | £1,120.70 |
The important feature isn't just the arithmetic. The £120.70 must be visible as a separate holiday pay line, so the worker can see what has been paid for holiday. Paying a larger combined amount without identifying the holiday component makes the arrangement difficult to verify and explain.
The calculation should be repeated for each pay period, based on that period's relevant pay. A worker whose earnings vary will therefore receive a variable holiday pay amount. That's one reason the method can suit irregular work, but it also means payroll records need to preserve the calculation behind every payslip.
For a broader explanation of the calculation and how it fits into UK payroll, see this UK holiday pay calculation guide.
The payment timing can feel counterintuitive. If the worker later takes leave, the business shouldn't treat that absence as creating a second holiday payment under the rolled-up method. The worker has already received the associated holiday pay, but the employer still needs accurate leave records so the entitlement to time away from work isn't lost.
Here's the video element for readers who prefer a visual explanation:
The Legal Journey From Banned to Conditionally Allowed
The current rules are difficult to understand if you remember the older position. Before the UK reforms, rolled-up holiday pay had been unlawful in all cases. Employers generally had to pay holiday pay when the worker took annual leave, rather than distributing it across earlier pay packets.
That position changed through the UK government's holiday entitlement and holiday pay reforms. The reforms took effect from 1 January 2024, but the new rolled-up holiday pay option applies only to leave years beginning on or after 1 April 2024, as set out in the government's holiday pay and entitlement reforms.
The dates employers need to separate
These milestones aren't interchangeable:
- 1 January 2024: the wider reforms took effect.
- 1 April 2024: the rolled-up holiday pay option became available for qualifying workers whose leave years begin on or after this date.
That distinction matters for businesses with different leave-year arrangements. The relevant question isn't whether payroll is being run after the reform date. You need to check when the worker's applicable leave year started.
The permission has a narrow boundary
The reform didn't make rolled-up pay lawful for everyone. It applies only to irregular-hours workers and part-year workers. For regular-hours employees, employers still can't include holiday pay in the hourly rate. Those workers must continue to receive holiday pay when they take their leave under the applicable traditional arrangements.
This creates a practical compliance sequence:
- Determine whether the worker is irregular-hours or part-year.
- Confirm that the relevant leave year starts on or after the applicable reform threshold.
- Choose whether to use rolled-up pay for that eligible worker.
- Apply the payment and payslip rules consistently.
A payroll system can calculate a percentage accurately, but it can't repair an incorrect worker classification. That decision sits with the employer and depends on the contract, expected working pattern and actual arrangement.
For small businesses, payroll accuracy is therefore part of compliance management, not merely an administrative task. A worker who starts on variable shifts may later develop a predictable pattern, while another employee's contract may change from year-round work to term-time work. Those changes should trigger a review rather than an automatic continuation of the original payment method.
The holiday pay changes explained for UK employers provide useful context, but employers should still examine each worker's circumstances rather than relying on a broad label such as “casual”.
The Real Advantages and Drawbacks to Weigh Up
Rolled-up holiday pay can make variable payroll easier to forecast, but it isn't just an administrative upgrade. It changes when workers receive money connected with their leave, and that can affect how they understand and use their entitlement.
For an employer managing seasonal shifts, the payment is linked directly to work completed in the pay period. That can make the cost of each payroll run easier to anticipate. It also avoids a later exercise in calculating holiday pay retrospectively when a short-term worker leaves, provided the arrangement has been operated correctly from the outset.
Workers may also value seeing a clearly labelled holiday payment on every payslip. The arrangement can make the holiday element visible instead of leaving the worker to infer it from a payment made when leave is taken.
Why the convenience has limits
The method has a defined scope. It's available only to the two qualifying categories, so a business can't adopt one approach across every employee just because that would be easier for payroll.
There's also a behavioural concern. If no separate pay arrives when a worker takes time off, they may feel they can't afford to stop working. The employer should explain the arrangement clearly and continue encouraging staff to take their leave. Paying holiday money early doesn't remove the need to protect rest and absence from work.
The main risk sits in classification
A regular-hours employee incorrectly treated as irregular may not receive the holiday pay they should have received when taking leave. The business could then face a dispute involving unpaid or underpaid holiday pay, alongside the work needed to reconstruct earlier payroll.
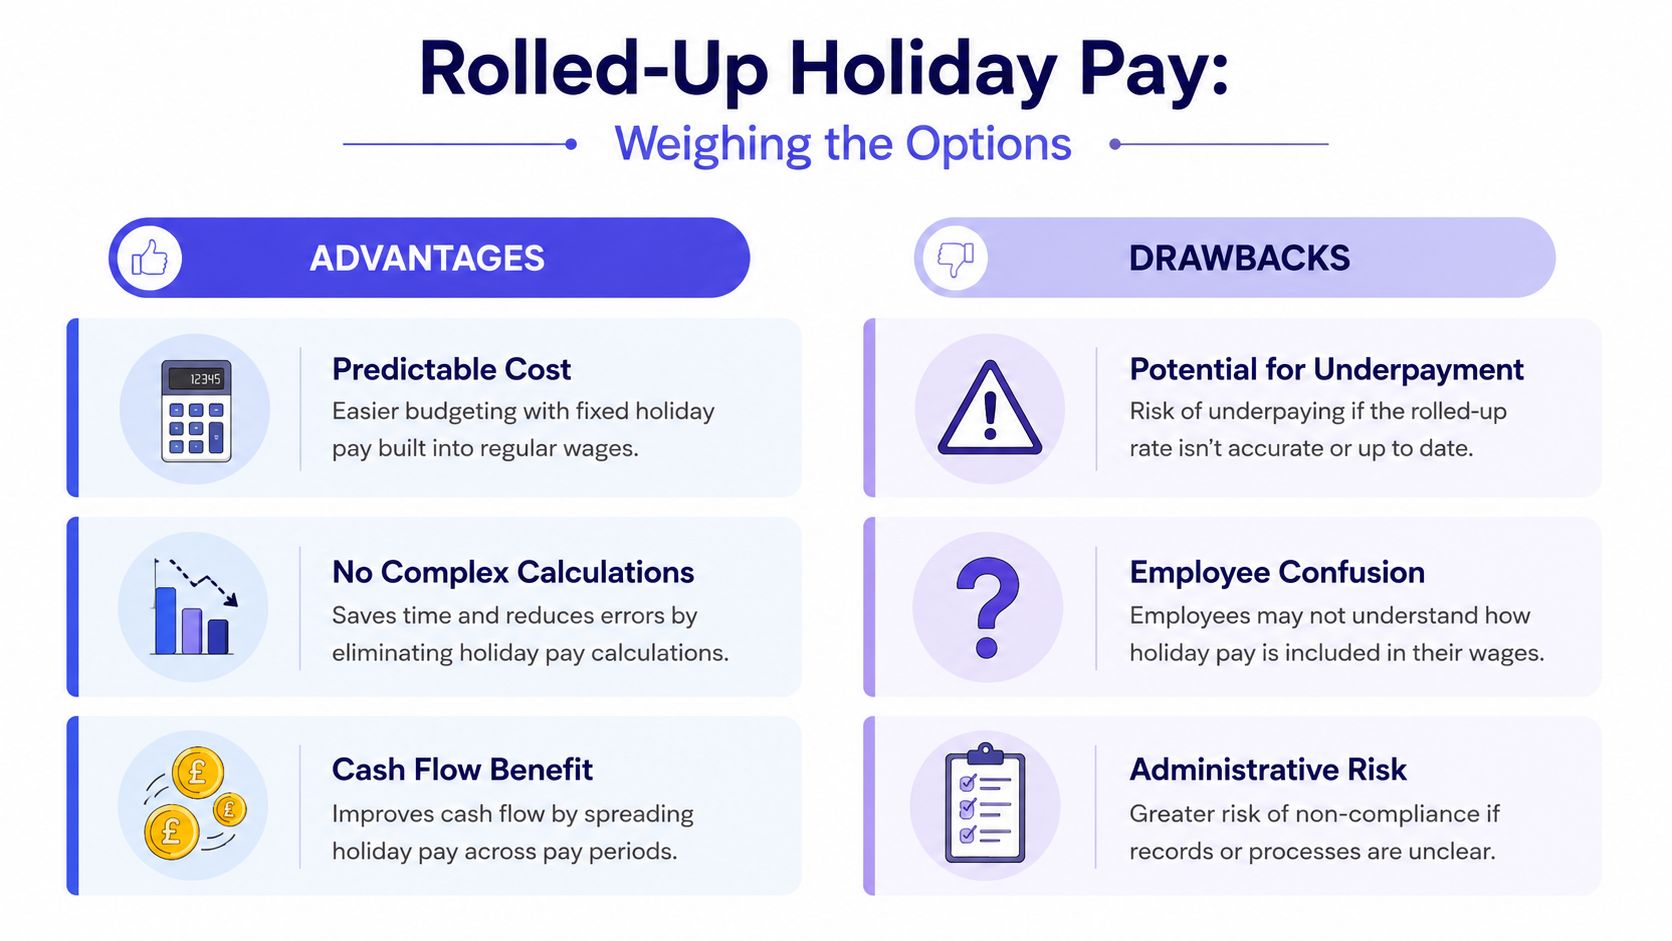
| Advantages | Drawbacks |
|---|---|
| Costs for variable work are easier to align with each pay period. | The method is restricted to specific worker categories. |
| Employers avoid some retrospective calculations for eligible workers. | Workers may misunderstand why no separate payment arrives during leave. |
| Holiday pay appears visibly on each payslip when itemised correctly. | Misclassification can create back-pay and compliance problems. |
The right question isn't “Is rolled-up pay easier?” It's “Does this method fit this worker, and can we explain and evidence it properly?” That shift keeps the decision focused on lawful administration and worker experience rather than convenience alone.
Choosing Between Rolled Up Pay and Traditional Accrual
Traditional accrual works in the way most employees expect. Holiday entitlement builds up, the worker books leave, and the employer calculates and pays the holiday pay when that leave is taken. Rolled-up pay distributes the holiday payment across the relevant pay periods instead.
A stable, regular-hours team will generally need the traditional approach because rolled-up pay isn't permitted for regular-hours employees. Seasonal, casual and term-time-only patterns may qualify, but eligibility still needs to be assessed worker by worker.
| Aspect | Rolled-Up Holiday Pay | Traditional Accrual |
|---|---|---|
| Eligibility | Irregular-hours and part-year workers only | Suitable for regular-hours workers and other arrangements where pay is made when leave is taken |
| Payment timing | Paid with wages for work completed in each pay period | Paid when the worker takes annual leave |
| Payslip treatment | Shown as a separate holiday pay line | Shown through the pay associated with the leave period |
| Cost predictability | Holiday pay follows pay for work completed | Holiday pay can arise when leave is taken |
| Administrative focus | Correct classification, period-by-period calculation and clear itemisation | Accurate entitlement, leave records and holiday pay calculation at the time of absence |
A practical decision rule
Use traditional accrual when the worker has a regular-hours arrangement or when paying at the time of leave best supports understanding and leave-taking. Consider rolled-up pay only where the worker qualifies, the leave year is eligible, and the business can maintain a clear record of each payment.
A mixed workforce may need both methods. That isn't a payroll failure. It's often the accurate result of having regular employees alongside irregular or part-year workers.
Before changing an arrangement, document why the worker qualifies and explain the payment timing to them. The guide to accrued holiday pay can help employers understand the alternative where holiday pay is connected to leave taken.
Avoid making the decision solely on the basis of software settings. A dropdown marked “casual” doesn't establish that a worker meets the legal category. The contract, leave year and working pattern remain the foundation of the choice.
Compliance Practices Every Small Business Should Follow
A payslip should let a worker answer one question quickly: which amount is ordinary pay, and which amount is holiday pay? Build your process around that question, then review it when contracts, working patterns or leave-year arrangements change.
Use a payroll checklist
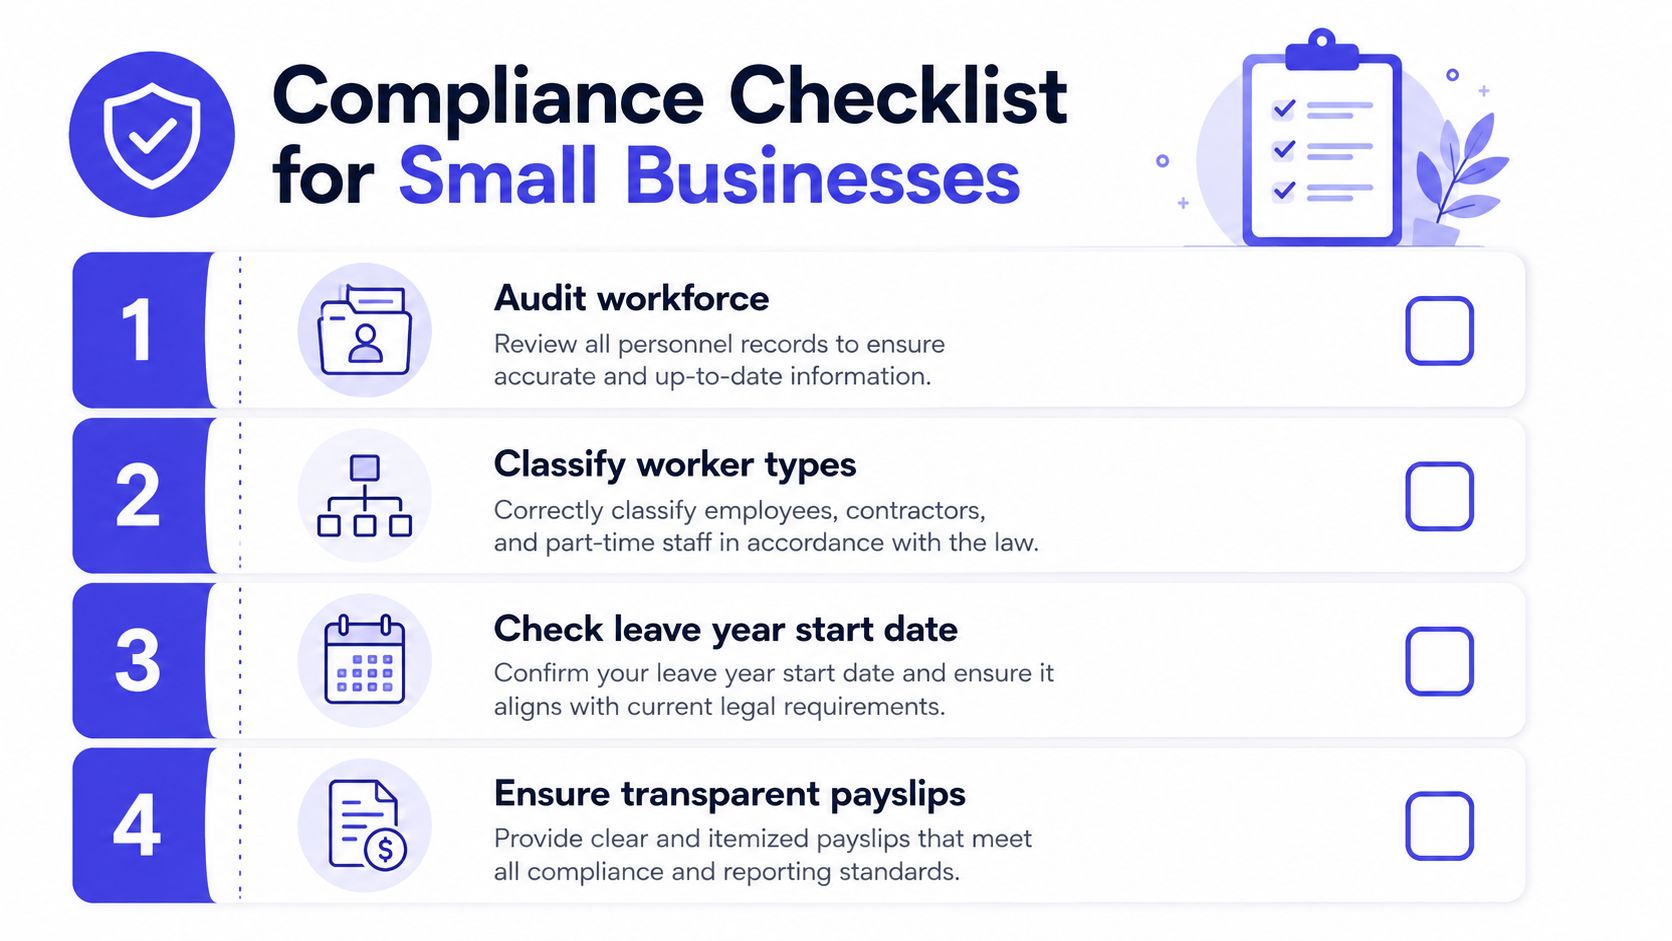
- Audit the workforce: List each employee and worker who receives, or may receive, a holiday pay supplement.
- Classify the worker: Confirm whether the person is an irregular-hours worker or a part-year worker. Job titles do not establish the category.
- Check the leave year: Verify that the worker's leave year begins on or after 1 April 2024, the threshold identified in the ACAS rules for rolled-up holiday pay.
- Calculate each period: Apply 12.07% to the relevant pay for the period, using the statutory method where it applies.
- Label the payslip: Show rolled-up holiday pay as a separate line from ordinary wages.
- Track leave taken: Keep entitlement and absence records even though the associated payment is made earlier.
- Review changes: Recheck the arrangement if an irregular pattern becomes stable or the worker's contract changes.
Keep evidence behind the payment
A separate payslip line explains the payment to the worker. Internal records should also show the pay-period basis, worker classification and leave-year information behind the figure. For example, if the relevant pay for a period is £500, the holiday element calculated at 12.07% is £60.35. The payslip should identify that £60.35 separately rather than folding it into ordinary wages.
Keep these records together where possible. Spreadsheets often place shifts, leave and payslip calculations on separate tabs. That setup can hide a changed working pattern or make an omitted payment harder to find.
Businesses replacing manual tracking can review Automated Payroll to assess how automation may support repeatable calculations and record-keeping. Software can reduce transcription and timing errors, but it cannot decide whether a worker belongs in the eligible category. Review the contract, working pattern and leave-year details before relying on a payroll setting.
Explain the arrangement in plain English. Tell workers that the separate holiday payment appears in their regular pay, explain what they will see when taking leave, and remind them that they still need to book and take their entitlement. Accurate records support the business, while a clear explanation helps workers understand and use their leave.
Making Holiday Pay Simple and Compliant
Rolled-up holiday pay is a narrowly scoped payroll option, not a blanket shortcut. The 2024 reforms made the worker's category and leave-year start date the first safeguards, before the calculation or payslip design even comes into view.
For an eligible worker, the routine is manageable: calculate the holiday element for the pay period, apply the 12.07% statutory method, pay it alongside wages and show it separately. Then maintain reliable records of entitlement and leave taken so early payment doesn't turn into poor holiday administration.
The most useful next step is a workforce review. Check which people work irregular hours, which work only part of the year, when each leave year begins and whether your payroll records explain every holiday payment. A leave management system such as LeaveWizard can help automate leave calculations, streamline approvals and maintain absence records alongside availability information.
That combination gives small businesses a clearer audit trail and gives workers a better explanation of what their payslips mean. It also supports a healthier workplace, because employees can take the leave they're entitled to without the business losing control of coverage or payroll accuracy.


